Asset focus
Hospitality & Leisure
Hospitality assets assessed through guest demand, seasonality and operating execution, with attention to what remains after distribution and service costs.
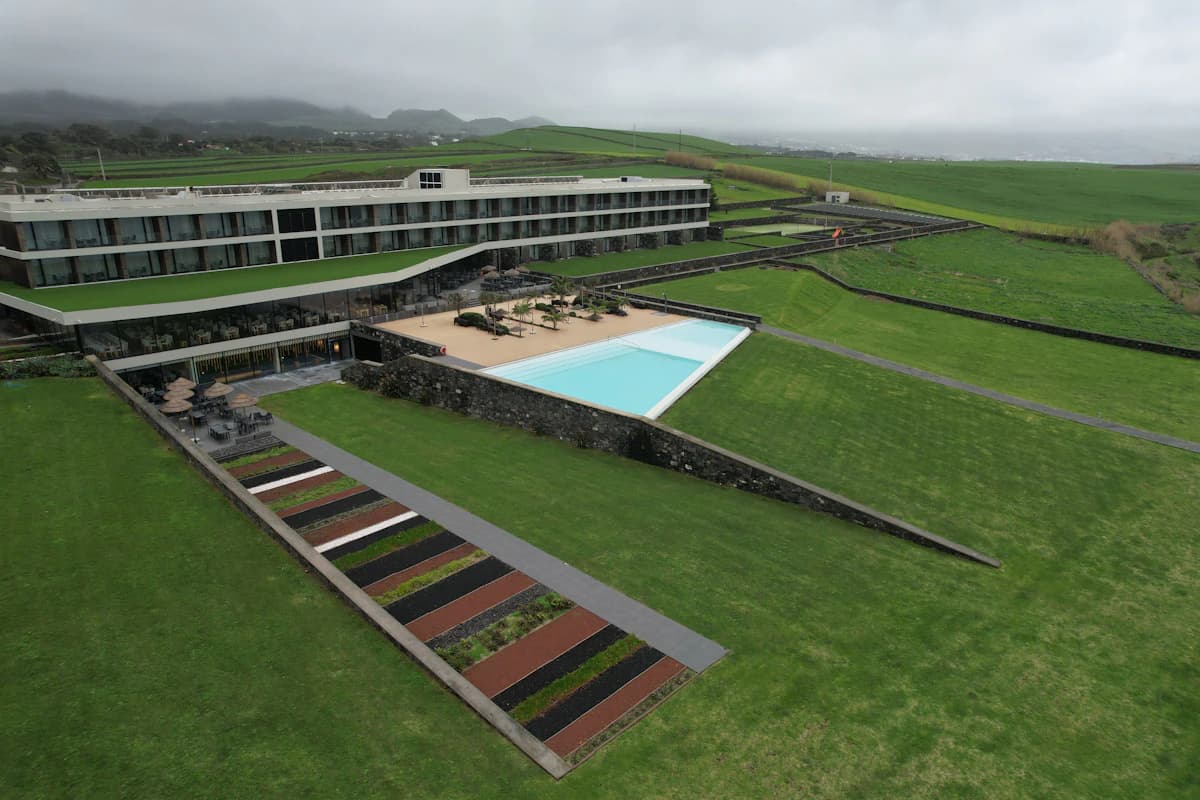
Scope of research
Understand the use. Then the economics.
- Hotels, serviced accommodation and leisure properties with a definable guest market and operating proposition.
- Repositioning and refurbishment opportunities where the physical building, operating permissions and operator model can be assessed together.
A research focus, not a statement of owned or managed assets.
01 / Demand
Who needs this space?
Separate business, leisure, group and repeat demand. Investigate why guests visit, how they arrive and what alternative accommodation they consider.
Review demand by month and day of week. A strong holiday period must not be treated as evidence for a full-year revenue assumption.
02 / Operating fundamentals
What the records need to tell us.
Occupancy and average daily rate
Read room nights sold and the realised room rate together, with consistent treatment of taxes, packages and complimentary rooms.
Revenue per available room
Room revenue divided by available room nights. It combines price and occupancy but does not measure profit.
Net channel contribution
Compare revenue after booking commissions, payment costs, promotions and other attributable distribution expenses.
Operating cost and renewal needs
Review staffing, utilities, guest services, operator fees and planned replacement of furniture and equipment.
03 / Practical improvements
A plan that can be delivered.
- Match the product and service level to identifiable guest needs and the location’s operating season.
- Improve room pricing and channel mix while tracking the net contribution of each booking source.
- Define operator responsibilities, maintenance standards and reporting routines before committing to a refurbishment plan.
04 / Before the next step
Questions worth asking.
01What generates demand outside peak dates, and how reliable is the supporting evidence?
Record the supporting documents, responsible party and any unresolved assumptions. This question should be answered for the specific property before advancing the assessment.
02Do operating permissions and building conditions support the intended guest experience?
Record the supporting documents, responsible party and any unresolved assumptions. This question should be answered for the specific property before advancing the assessment.
03Who bears working capital, refurbishment and replacement costs under the operator agreement?
Record the supporting documents, responsible party and any unresolved assumptions. This question should be answered for the specific property before advancing the assessment.
04How would a weaker season affect payroll, reserves and debt payments?
Record the supporting documents, responsible party and any unresolved assumptions. This question should be answered for the specific property before advancing the assessment.
Bring a specific opportunity